Real Estate Wire Fraud: How Scammers Hijack Closing Instructions and Steal Down Payments


Key Takeaways
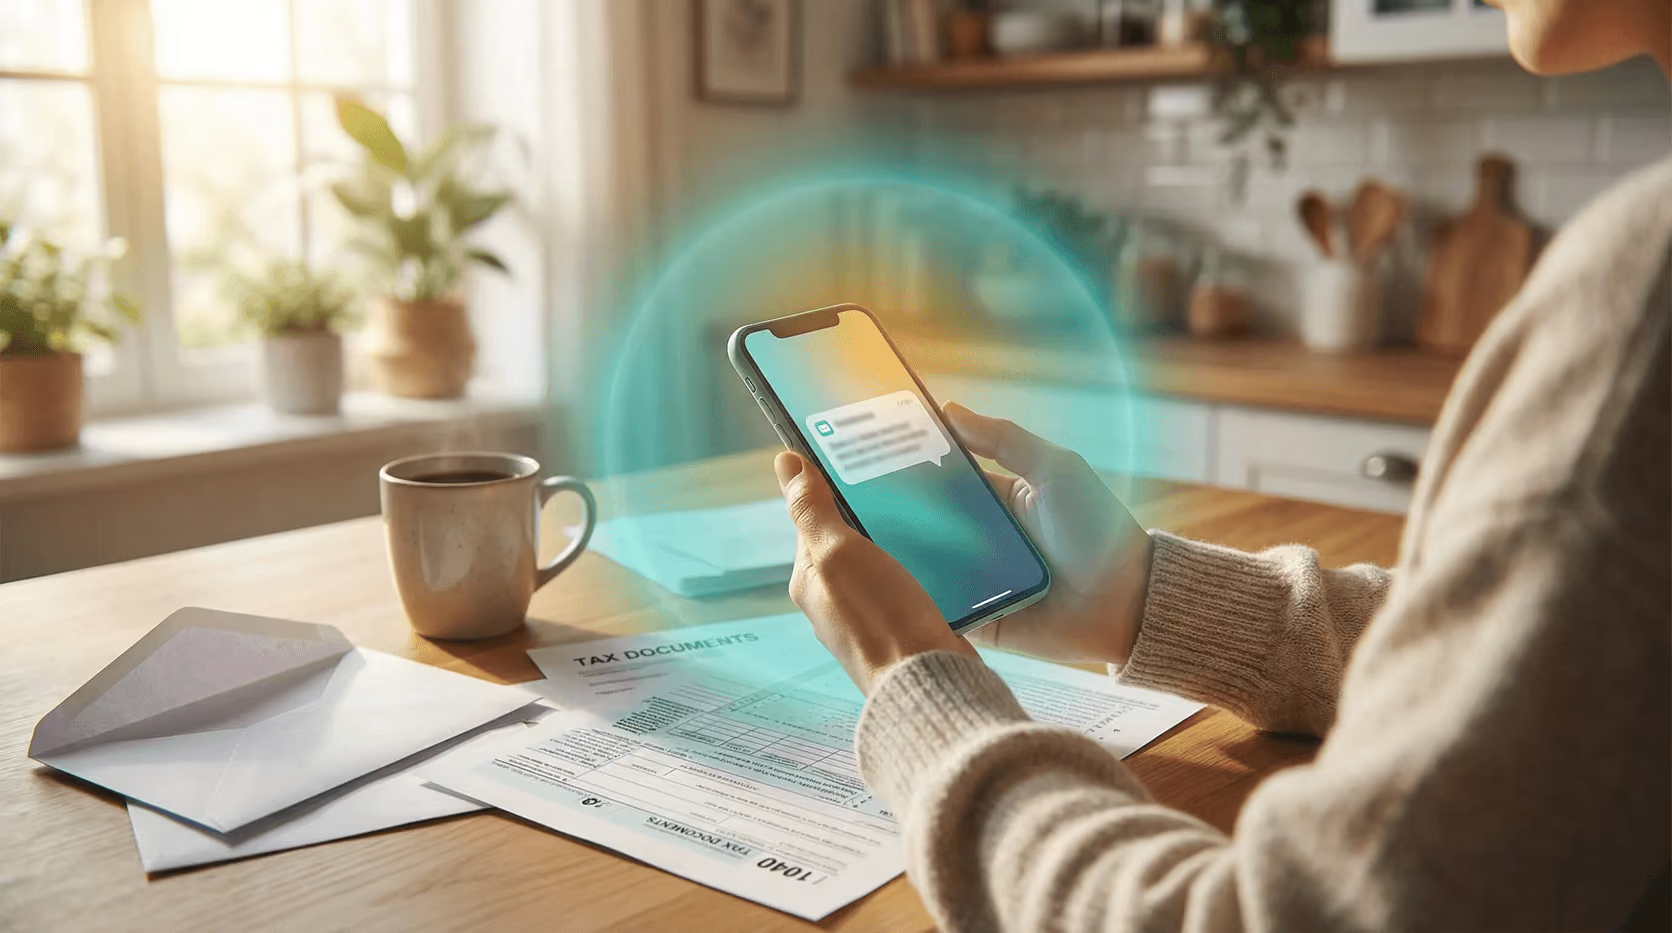
You've found the house. You've signed the paperwork. Closing day is finally here, and then one email changes everything.
It looks like it's from your title company. It has the right logo, the right language, even the correct property address. But those new "updated" wire transfer instructions? They don't lead to your closing agent. They lead straight to a criminal's bank account.
This is real estate wire fraud, and it's costing American homebuyers hundreds of millions of dollars a year.
The numbers are staggering
Real estate wire fraud isn't a rare edge case. It is one of the fastest-growing financial crimes in the United States, and it specifically targets people at their most financially vulnerable moment.
According to the FBI's Internet Crime Complaint Center (IC3), in 2025, scammers filed over 12,368 real estate fraud complaints with reported losses surpassing $275 million FBI IC3. That's up from $173.6 million across 9,359 complaints in 2024, a dramatic year-over-year jump.
Business Email Compromise (BEC), the primary method used to execute these scams, caused $2.77 billion in total losses across all industries in 2024, making it one of the three most financially damaging forms of cybercrime tracked by the FBI.
And the victims aren't just wealthy investors. According to the 2025 State of Wire Fraud Report by CertifID, first-time homebuyers are three times more likely to fall victim than experienced buyers or sellers. These are everyday people transferring their life savings, often for the very first time.
Real estate wire fraud is the kind of crime that can wipe out years of savings in a single afternoon.
How the scam actually works
Real estate wire fraud is a precision attack. Scammers don't randomly spam inboxes, they infiltrate, observe, and strike at exactly the right moment.
Here's the anatomy of a typical attack:
Step 1: Email infiltration
A cybercriminal hacks or spoofs a legitimate email account belonging to your real estate agent, title company, or closing attorney. In many cases, they don't even need to break in, they simply create a look-alike email address that differs by one character (e.g., title_company@closingfirm.com becomes title_company@cl0singfirm.com).
Step 2: Silent surveillance
Once inside the email thread, the fraudster goes quiet. They read weeks of correspondence. They learn the buyer's name, the property address, the expected closing date, and the dollar amounts involved. They wait.
Step 3: The fake wire instructions
Days before closing, when urgency is highest and emotions are running hot, the scammer sends a carefully crafted email. It mimics the tone, formatting, and branding of your title company. It announces a "change" or "update" to the wire transfer instructions and provides new banking details.
The email feels routine. It sounds professional. And it lands at exactly the moment you're expecting to hear from your closing agent.
Step 4: The wire goes out, and vanishes
The buyer follows the instructions, wires tens or hundreds of thousands of dollars, and confirms the transfer. By the time anyone realizes something is wrong, the money has been moved through a chain of accounts, often internationally, and is nearly impossible to trace.
One Utah couple wired $297,778, their entire life savings, to a fraudster after receiving a spoofed email from their "title company." The phone number listed in the documents had been disconnected. Their bank confirmed the transfer had already processed. They were fortunate: the funds were later recovered through a fraud recovery service, but that outcome is the exception, not the rule. Most victims never see the money again.
Why real estate is such a ripe target
Fraudsters don't choose real estate by accident. The industry has several characteristics that make it uniquely vulnerable:
- High dollar values. A single successful hit can yield six or seven figures.
- Time pressure. Buyers are often rushed, emotionally invested, and under deadline pressure at closing.
- Publicly available data. Property records, MLS listings, and county records give scammers detailed transaction intelligence, for free.
- Lax cybersecurity standards. Many real estate businesses don't have enterprise-level IT infrastructure. Cybersecurity requirements vary by state, leaving wide gaps in protection.
- Low consumer awareness. According to CertifID's 2025 report, 52% of homebuyers were "not aware" or only "somewhat aware" of wire fraud risks before the closing process. Fewer than half (49%) were first warned about wire fraud by their own real estate professional.
Red flags to watch for
Knowing what to look for can save your down payment. Be immediately suspicious if:
- You receive a last-minute email with "updated" wire instructions. Legitimate title companies rarely change wiring details at the eleventh hour. If they do, they will confirm by phone, using a number you look up yourself, not one provided in the email.
- The sender's email address looks slightly off. Scammers use domains like
closingfirm-us.comor swap letters (rnform). Always scrutinize the full email address, not just the display name. - The email creates urgency. Phrases like "wire immediately to avoid delays" or "updated instructions, action required today" are manipulation tactics built to bypass your critical thinking.
- You're asked to keep the change confidential. Any request to not verify with your closing agent is a guaranteed red flag.
- The wire instructions differ from documents you signed. Compare any new instructions against your original closing disclosure or escrow documents.
- You get a phone call confirming new instructions from a number you didn't initiate. Scammers also use phone spoofing. If someone calls you to "confirm" a wire change, hang up and call your title company directly using a number from their official website.
How to protect yourself before closing
Prevention is far more effective than recovery. Here's what to do:
Verify everything by phone, but call the right number
Before wiring any money, call your title company or closing attorney to verbally confirm the wire transfer details. Use the phone number from their official website or a signed document you received at the beginning of the transaction. Never use a number provided in a last-minute email.
Establish a code word with your closing team
At the beginning of the transaction, agree on a verbal passphrase with your title company. Any legitimate communication about wiring instructions should include that code.
Use secure document portals when available
Many title companies now offer encrypted portals for exchanging sensitive information. If your title company provides one, use it, and be skeptical of any wire instructions that arrive outside that channel.
Enable multi-factor authentication on your email
Email compromise is the gateway to this crime. Enabling two-factor authentication (2FA) on your email account makes it significantly harder for scammers to infiltrate your communications.
Ask your title company about wire verification tools
Companies like CertifID offer real-time wire transfer verification services. In 2025 alone, CertifID's platform verified over 1.46 million wire transfers and prevented $283 million in fraudulent transfers, blocking over 1,000 fraudulent wires. If your title company uses such a tool, that's a meaningful layer of protection.
Slow down, even when you feel pressure to move fast
Scammers bank on urgency. If anything about your wire instructions feels rushed or unexpected, stop. A legitimate closing can absorb a short delay. Your life savings cannot.
What to do if you've already wired money to a fraudster
Speed is everything. Every minute counts.
Act within the first 24-72 hours:
- Call your bank immediately. Ask them to recall the wire transfer and freeze the transaction. If the funds haven't fully cleared the receiving account, recovery may still be possible.
- File a report with the FBI's IC3 at ic3.gov. The FBI's Recovery Asset Team (RAT) can initiate a Financial Fraud Kill Chain. In 2024, this process helped freeze or recover 66% of attempted stolen funds when victims reported quickly FBI IC3.
- Contact the FTC at ReportFraud.ftc.gov.
- File a police report with your local law enforcement agency.
- Notify your title company and real estate agent so they can warn other clients and investigate how the breach occurred.
- Contact your state's Attorney General and, if applicable, your state's real estate regulatory board.
Don't wait. Don't hope it resolves itself. The 72-hour window is real, after that, the chances of recovery drop sharply as funds move through the international banking system.
A final word: why this scam works
Real estate wire fraud is not a crude, obvious attack. It is a carefully engineered crime that exploits trust, timing, and the high-stakes emotions of buying a home. The email you receive will look authentic. The language will feel familiar. And it will arrive at exactly the moment you least expect to question it.
That's the point.
Your best defense is a simple habit: never wire money based on emailed instructions alone. Always verify. Always call. Always use a number you trust from a source you verified before the transaction began.
The stakes are too high, and the criminals too sophisticated, to do anything less.
Conclusion
The pattern behind every real estate wire fraud case is the same: a scammer patient enough to watch and wait, and a moment engineered to make you act before you think. Treat any last-minute change to wire instructions as a red flag, not an inconvenience.
If you've been targeted by real estate wire fraud, report it immediately to the FBI IC3 at ic3.gov and your bank's fraud department. Time is the most critical factor in fund recovery.
FAQs
What is real estate wire fraud?
Real estate wire fraud is a scam where criminals intercept or spoof email communications during a home purchase and send fake wire transfer instructions, redirecting your down payment or closing funds to a fraudulent bank account. Scammers infiltrate email threads, learn transaction details, and send convincing fake instructions at the most critical moment, often days before closing.
How common is real estate wire fraud?
Real estate wire fraud is widespread and growing. From 2020 through 2025, Americans reported more than $1.5 billion in real estate fraud losses to the FBI, according to IC3 annual reports. In 2025, the FBI's IC3 received over 12,368 real estate fraud complaints with losses exceeding $275 million, up from $173.6 million in 2024.
How do I know if a wire transfer email is fake?
Fake wire transfer emails typically arrive last-minute with 'updated' banking instructions, create urgency with phrases like 'wire immediately,' and use email addresses that look slightly off, such as swapped letters or added hyphens. Always verify wiring instructions by calling your title company using a phone number from their official website, never from the email itself.
Can you recover money lost to wire fraud?
Recovery is possible but only if you act within 24 to 72 hours. Call your bank immediately to request a wire recall, then file a report with the FBI's IC3 at ic3.gov so the Recovery Asset Team can initiate a Financial Fraud Kill Chain. In 2024, this process helped freeze or recover 66% of flagged funds when victims reported quickly. After 72 hours, recovery becomes significantly harder.
Who is most at risk for real estate wire fraud?
First-time homebuyers are most at risk. According to CertifID's 2025 State of Wire Fraud Report, first-time buyers are three times more likely to fall victim than experienced buyers or sellers. Low awareness is a key factor: 52% of homebuyers said they were 'not aware' or only 'somewhat aware' of wire fraud risks before closing.
What should I do immediately after falling for real estate wire fraud?
Call your bank immediately and ask them to recall the wire transfer. Then file a report with the FBI's IC3 at ic3.gov, contact the FTC at ReportFraud.ftc.gov, file a local police report, and notify your title company and real estate agent. Every hour matters: the Financial Fraud Kill Chain is most effective within the first 24 to 72 hours after the transfer.
How do scammers get access to real estate email threads?
Scammers access real estate email threads by hacking email accounts belonging to agents, title companies, or closing attorneys, or by creating look-alike email addresses that differ by one character. Once inside, they monitor the conversation for weeks to learn names, amounts, and closing dates before sending fraudulent wire instructions at the most convincing moment.
 How-To & Safety Tips
Spring Cleaning for Your Computer: Inside and Out